advertisement
Recent Posts
Featured Posts
Most Read
Harnessing Trade, Digital Innovation, and Connectivity for ASEAN's Growth
The Association of Southeast Asian Nations (ASEAN), in response to the evolving global economic dynamics, has the opportunity to strengthen economic stability and sustainable growth through a focus on trade, tourism, and digital advancement. In today's competitive global marketplace, countries are reassessing their supply chains to reduce vulnerabilities and are adopting protectionist policies to support local industries. Moreover, issues like climate change and the race for advanced technologies such as AI and big data are increasingly considered from a national security perspective. Within this context, the ASEAN community, consisting of 10 member states, must work together to ensure a prosperous economic future and to protect their national interests, with a particular focus on trade, digitalization, and connectivity. Trade, particularly in services, is set to be a key driver for ASEAN economies, including sectors like finance, telecommunications, tourism, transportation, and professional services. These areas are essential for job creation and economic growth. After the pandemic, while trade in goods has decelerated, service trade has shown an upward trend, positioning ASEAN as a net exporter of services. Tourism offers significant potential for ASEAN, showcasing the region's allure as a travel destination. To enhance competitiveness in tourism, ASEAN countries are expected to collaborate on infrastructure, skill development, marketing, and product innovation to increase intra-regional travel, which currently represents over 40% of ASEAN's international tourism, thus bolstering regional economic resilience. The regional digital economy, encompassing e-commerce and digital health, is expected to grow from $300 billion to nearly $1 trillion by 2030. With effective policies on digital connectivity through regional cooperation, this growth could be doubled. The Digital Economy Framework Agreement is crucial for this collaboration, covering areas such as digital standards, data flows, cybersecurity, digital trade, and the mobility of digital talent, among other components of digital public infrastructure. Digital collaboration is also expected to bring additional benefits, including positive environmental effects, social cost savings of $12-30 billion, increased resilience, job creation, and improved access to education and healthcare. Furthermore, both physical and institutional connectivity are vital for ASEAN's economic competitiveness, enhancing engagement with larger Asian and global economies. Sustainable infrastructure, including renewable energy, low-carbon transport, and urban energy efficiency, is gaining traction. By integrating this with enhanced digital cooperation and streamlined cross-border logistics and supply chains, facilitating the movement of goods, services, and people across borders will protect the environment and strengthen regional resilience. The collective approach to sustainable infrastructure is advantageous for ASEAN members committed to the Paris Agreement, with Nationally Determined Contributions aiming for net-zero CO2 emissions by 2050 and net-zero greenhouse gas emissions by 2065, to cap global temperature increases at 1.5°C. It is a strategic moment for ASEAN policymakers to reconsider collaboration. Amidst global economic fragmentation, there are areas that require cross-border cooperation. Economic self-reliance has increased in the region, and with pressing issues such as digitalization and climate change, mismanaged interdependence could lead to costs and economic challenges. Therefore, for the upcoming term of ASEAN regional cooperation until 2045, member countries should regard their collective actions as a regional public good, where the benefits of enhanced trade, tourism, digitalization, and connectivity will result in sustainable and resilient outcomes for the region's population.
Business agenda: Sustainable air travel with Helsinki Citycopter and Canadian companies making the most of Trump’s tariffs
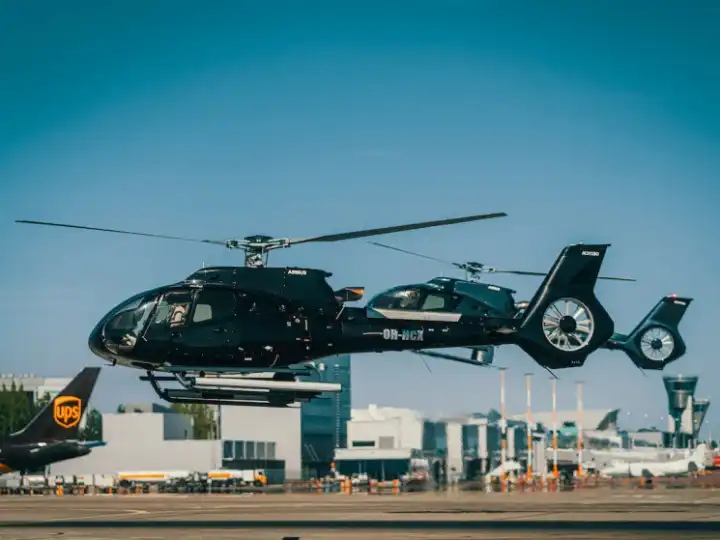
Technology: USAGood vibrationsThis NBA season, blind and low-vision basketball fans have been able to follow the action from their arena seats using a handheld device that describes the game through vibrations. Seattle-based start-up OneCourt was founded in 2021 and its haptic device debuted with the Portland Trail Blazers in January. The technology uses wi-fi and 5G to transmit data from arena sensors and cameras; coupled with a live broadcast, fans who can’t see the game can follow the action as the device signals, for example, where a three-point shot was taken. The early-stage start-up has raised $475,000 (€420,000) from angel investors, including Microsoft’s ceo, Satya Nadella, and five NBA teams have signed up for the service. OneCourt has also engineered versions for baseball and football, which could be used during the Fifa Club World Cup that kicks off on 14 June. Co-founder Jerred Mace and his team currently make the OneCourt device in-house but he hopes to produce it at scale for an underserved market of sports fans who will be able to use it at home too. “We want to have a product that doesn’t just live in the stadium,” he says.Transport: FinlandOut for a spinPrivate helicopter transfers tend to be functional affairs, with cramped cabins and the lingering scent of jet fuel. Helsinki Citycopter, a Finnish firm founded in 2020, does things differently: the five helicopters in its fleet, which includes two Airbus ACH130s and an H125, have spacious interiors with leather seats, noise-cancelling headsets and efficient climate control. Powered by sustainable aviation fuel and modern low-emission engines, the aircraft also leave a smaller environmental footprint than many of their competitors. “There’s a unique advantage to helicopter travel,” says co-founder Joonas Nurmi, who spent 15 years with Finnair. “You get perspectives that you don’t see from a plane or car and you can land almost anywhere.”Now the market leader in northern Europe, the company has steadily expanded, adding a Cessna Citation CJ4 private jet to its portfolio and launching a flight academy for helicopter and fixed-wing pilots. In addition to transfers, the firm enables travel to remote destinations, including Lapland, the Finnish archipelago and the Lofoten Islands. “Our product is nature,” says Nurmi. “And we fly where no one else does.”helsinkicitycopter.comAgriculture: CanadaGrowth opportunityWhen Donald Trump launched his first tariff broadsides at Canada’s economy in February, Canadian shopping habits shifted abruptly – away from American-made goods and towards more homegrown brands. That presents an opportunity for independent Canadian food companies. Among them is Lufa Farms, the innovative urban agriculture firm and marketplace for Québec-grown produce, which was co-founded in Montréal in 2009 by Lebanese engineer and entrepreneur Mohamed Hage and is currently expanding its reach across the country.Inspired by the rooftop fruit-and-vegetable gardens that are a fixture of urban life in Hage’s home country, Lufa Farms operates as a network of rooftop hydroponic greenhouses on the flat roofs of industrial buildings, warehouses and big-box retail complexes in Montréal and across the broader region. The vegetables cultivated inside, which are watered by a system of rainwater- and ice-melt collection from the greenhouse roofs, are then picked and assorted into weekly grocery baskets. Lufa Farms’ urban greenhouses not only reduce the distance between farm and table but have also activated parts of the existing urban fabric that have too long been dormant. Hage now operates an indoor farm and five greenhouses across the region, which serve about 35,000 customers every week, and has expanded deliveries to Ottawa. Lufa Farms’ success sends a strong signal that customers have a healthy appetite for this kind of urban agriculture – and that there’s ample room to grow.lufa.com
Navigating the Financial Journey: Tailored Strategies for Life's Chapters
Financial planning is an individualized process that adapts to the unique financial circumstances and goals at different life stages. As individuals progress through various phases, their financial priorities shift, necessitating a dynamic approach to financial planning. This article delves into the pivotal financial strategies for each life stage, from the early years of adulthood to the golden years of retirement, offering insights on crafting a flexible financial plan that adapts to life's changes. 1. Young Adulthood (Ages 20-30): Establishing Financial Footing Young adulthood is a pivotal period marked by career beginnings, financial independence, and critical financial decisions. This is the opportune time to establish a robust financial base for the future. Budgeting and Emergency Funds: Cultivating budgeting habits is paramount. It's essential to balance income and expenses and allocate funds for emergencies and future objectives. A priority is to establish a savings account for immediate goals and an emergency fund covering 3-6 months of living expenses. Education Loan Management: For many, managing student loans is a priority. Formulating a repayment strategy is vital, which may involve additional payments to expedite loan settlement or loan consolidation for more favorable interest rates. Investigating forgiveness and refinance options is also advisable. Retirement Investment: Though retirement may seem distant, it's beneficial to start contributing to retirement accounts like a 401(k) or IRA early on. The benefits of compound interest mean that even modest contributions in your 20s can accumulate significantly over time. Credit Building and Debt Avoidance: At this stage, it's crucial to build and maintain a good credit score. Utilizing a credit card responsibly can bolster credit history. It's also wise to avoid incurring high-interest consumer debt that could become a future burden. 2. Career and Family Building (Ages 30-40): Enhancing Financial Stability Entering the 30s, financial complexities often increase with career advancement, homeownership, and family formation. Meticulous planning is essential for long-term financial health. Home Purchasing: Homeownership is a significant financial step for many. It's crucial to assess your budget to determine an affordable home price, considering all associated costs. Building equity through additional mortgage payments is also beneficial. Retirement Savings: Maximizing retirement account contributions is recommended, especially with employer matching. As income grows, so should retirement savings, and diversifying strategies with a Roth or traditional IRA can be advantageous. Insurance and Estate Planning: Securing appropriate insurance coverage is vital, particularly for those with dependents. Life insurance is critical for financial protection, and drafting a will and estate plan, regardless of asset size, is prudent. Education and Goal Savings: For parents, saving for children's education becomes a priority. A 529 plan offers tax benefits for education savings. Saving for other goals, such as travel or a secondary residence, also becomes more pertinent. 3. Middle Age (Ages 40-50): Refining Financial Goals In middle age, with milestones like career progression and child-rearing behind, the focus shifts to reassessing and adjusting financial objectives for a secure future. Boosting Retirement Savings: As retirement nears, maximizing retirement account contributions is key. "Catch-up" contributions for those over 50 can help those lagging in savings. Increasing savings rates to prepare for retirement is crucial. Investment Strategy Review: Nearing retirement, it's important to reassess investments. While younger individuals might embrace risk, those in their 40s and 50s should consider a more balanced, less volatile portfolio to protect and grow wealth. Education and Major Expense Planning: Education funding for children becomes a priority amid rising tuition costs, necessitating increased contributions. Other significant expenses, like elder care or life events, should also be considered. Estate Plan Updates: Reviewing and updating estate plans is important, especially with life events that may require changes. Long-term care insurance can also
The Influence of Political Stability on Fiscal Space Amidst Climate Risks
Climate risks have a profound impact on fiscal space, with sovereign bond yields and debt ratings serving as indicators of the financial challenges. The role of political stability and financial development in reducing these risks is pivotal, highlighting their significance for fiscal sustainability in the long run. Climate risks, encompassing the potential negative socio-economic consequences of climate change, pose considerable fiscal threats, particularly through their impact on fiscal space. For instance, a major disaster triggered by climate change could require substantial fiscal expenditures for relief and recovery efforts. Similarly, extreme heat due to global warming might lead to significant agricultural damage, prompting governments to offer subsidies to affected farmers. Broadly, public spending on climate change adaptation and mitigation stands as one of the largest fiscal demands globally. Combined with other significant fiscal demands, such as those stemming from an aging population, climate change-related fiscal expenditures pose a substantial threat to fiscal space and sustainability in the future. A recently published ADB Economics Working Paper analyzes the effect of climate risk on fiscal space across 199 countries from 1990 to 2022. We measure fiscal space using sovereign bond yields and ratings on foreign currency long-term sovereign debt. Elevated sovereign bond yields and downgraded sovereign debt ratings signal higher borrowing costs and default risks, indicating a deterioration in fiscal space. We also explore the mitigating role of political stability and financial development in climate-related fiscal risks. Specifically, we assess whether more politically stable and financially developed economies are less susceptible to these risks. Political stability is likely to reduce these risks as it increases the probability of more sustainable fiscal policies, such as a robust medium-term fiscal framework. Consequently, a more stable political environment is likely to lessen the impact of climate shocks and other shocks on fiscal sustainability. Moreover, political stability fosters more cautious, rational, and cost-effective government planning in response to potential climate shocks, helping to preserve fiscal space. Financial development is also anticipated to reduce climate-related fiscal risks. In financially developed economies, businesses and households have access to insurance and other financial instruments that protect them from the adverse effects of climate shocks. This reduces the need for substantial fiscal outlays, thereby mitigating the negative impact on fiscal space. Additionally, financial development increases the credit available to businesses and households to help them absorb the effects of potential climate shocks. Our findings reveal that a one-unit increase in climate vulnerability results in a significant one percentage point increase in bond yields in countries with high political stability risks, peaking at 2 years post the initial impact. Conversely, in countries with lower political stability risks, the response of bond yields is not statistically significant. In the case of financial development, economies with low financial development are more vulnerable to climate-related sovereign risks. Bond yields rise by approximately 0.6 percentage points for these economies, peaking at 2 years post the initial climate shock. Meanwhile, in economies with high financial development, no significant effect is observed. Overall, our empirical analysis indicates that climate vulnerability negatively affects fiscal space, with the most pronounced effects in countries most susceptible to climate change and where fiscal space is most limited. We also find that these effects are reduced in countries with more stable political environments and more developed financial markets. More specifically, our evidence shows that climate risks are associated with lower bond risk premiums and higher sovereign ratings in countries with less exposure to both external and internal conflict. Furthermore, better financial development weakens the link between climate risks and fiscal space. Financially developed countries do not experience a climate-related bond risk premium or a persistent decline in sovereign ratings due to climate vulnerability. While fiscal consolidation is crucial for mitigating the adverse effects of climate risks on fiscal space, our results suggest that political stability and financial development can also contribute. Political stability is valuable in its own right, but our analysis provides evidence of a significant additional benefit in protecting fiscal space from climate risk. Similarly, our findings reinforce the argument for governments to promote financial development further.
Navigating International Payments: Your Guide to Global Transaction Methods
Cross-border payments, also known as international money transfers, use advanced methods to move funds between countries. These transactions are crucial for companies that work with, purchase from, hire, or deal with international partners. When making these transfers, money often changes from one currency to another. It’s essential to follow the rules, banking practices, and exchange rates of both the sending and receiving countries carefully before processing international credit card transactions. Thanks to various advanced payment methods, many businesses can grow by leveraging exchange rates. These payments are used to buy from foreign sellers, pay employees in different countries, and receive payments from international customers. Best Methods for International Payments To find the best international credit card processing method, you need to conduct thorough research. Businesses can choose from the following foreign payment providers: 2Checkout 2Checkout, now part of Verifone, accepts payments from over 200 markets, making it ideal for European companies looking for overseas payment platforms. With no annual fees and free payments from European customers, it might be a cheaper option than larger names. However, with fees starting at 3.5% + 25p, it's mainly suited for European transactions. Opayo Opayo (formerly SagePay) offers three service levels: Flex, Plus, and Corporate. It supports multiple currencies and major credit and debit card companies. While Opayo offers a monthly fee option, its pricing isn't clearly stated on the website, making it hard to compare with other payment processors. Braintree Owned by PayPal, Braintree operates independently, providing businesses with their accounts to handle sales. Supporting over 45 countries, it's a solid choice for those seeking a foreign payment platform. General rates are 1.9% + 20p per transaction, with an additional 1% fee for cards issued outside the UK. PayPal PayPal is a popular, secure choice for online purchases, ideal for startups and small businesses due to its simplicity and reputation. It supports 25 different currencies and operates in over 200 countries and regions, making it a global option. PayPal's fees vary by currency, and international transactions can cost up to 5% + 3% in currency conversion fees. Worldpay Worldpay is an all-in-one payment service that allows websites or apps to accept international credit card payments securely. It operates in over 40 countries and supports 120 currencies. However, it requires long contracts (three years with automatic rollover) and may charge early termination fees. Pricing transparency is another issue, with both monthly fees and pay-as-you-go options unclear. Stripe Stripe offers various payment channels, allowing businesses to integrate new payment methods into their online stores easily. It supports over 135 countries and offers extensive local payment options. However, while convenient for online shops and eCommerce companies, card payments can come with high fees and potential failures. Amazon Pay Amazon Pay is a newer player in the payment scene but offers a user-friendly interface and multi-currency capabilities, making it ideal for international business growth. Starting at 2.7% + 30p per transaction, plus a cross-border fee of 0.4% to 1.5%, the fees can be high, and cheaper platforms might be preferable if users don't favor Amazon Pay. Adyen Adyen supports over 30 currencies worldwide, making it a great choice for businesses expanding into new regions. It offers a customizable online payment experience. However, its pricing is more complex, with both fixed processing fees and payment method-based fees, making it challenging to determine the total cost. Challenges Faced in International Payments While international transactions can enhance corporate operations, they come with two major drawbacks: Regulatory Hurdles Complicated and sometimes conflicting regulatory systems, such as data privacy rules, can be tough to navigate. Legal restrictions on money transfers can be confusing, and some companies might find these extra steps discouraging, potentially halting international transactions. Security Concerns Fraudulent activities such as data theft, unauthorized transactions, and account takeovers are risks in complex international payment systems. Online payment systems like Shopify implement robust security measures to combat these threats. By understanding and navigating these challenges, businesses can effectively manage international payments and leverage global opportunities to grow and succeed.
The Influence of Behavioral Economics on Financial Choices: Delving into the Mental Aspects of Money Management
Managing personal finances is often perceived as a simple numerical task: income, savings, investments, and expenditures. Yet, in practice, individuals frequently stray from rational choices due to psychological influences. Behavioral economics, a discipline that merges psychology and economics, aims to clarify why individuals frequently make financial decisions that aren't in their best interests. Our financial decisions are swayed by cognitive biases, emotions, and societal pressures, leading to outcomes that are less than ideal. Gaining an understanding of these biases can enhance one's financial decision-making and lead to more effective financial planning. This piece will delve into the core principles of behavioral economics, outline common cognitive biases that impact financial choices, and offer strategies to overcome these biases for improved financial results. 1. What Does Behavioral Economics Entail? Behavioral economics examines the role of psychological factors in shaping economic decisions. While classical economics posits that individuals act rationally to maximize their utility, behavioral economics acknowledges the impact of non-rational elements such as feelings, cognitive biases, and societal influences. People may make poor financial decisions even when they understand the long-term advantages of saving, investing, or debt repayment. Behavioral economics seeks to explain these deviations in human behavior by drawing on knowledge from psychology, neuroscience, and related fields. By comprehending how psychological factors influence financial decisions, individuals can become more aware of their inclinations and adopt measures to reduce the adverse impact of biases. 2. Typical Cognitive Biases in Financial Decision-Making Behavioral economics has uncovered several cognitive biases that affect individuals' financial behaviors. Here are some of the most prevalent biases that influence financial choices: Loss Aversion: Individuals often have a heightened fear of losses compared to the value they place on gains. This can result in overly cautious financial behaviors, such as retaining unprofitable investments or avoiding risk entirely. Loss aversion can also lead to excessive spending to evade the sensation of "losing" when parting with possessions. Status Quo Bias: There's a tendency to prefer the current state of affairs, even when change could be advantageous. This can be seen in financial decisions like maintaining high-interest debt or continuing to pay for unnecessary services. Status quo bias can also result in sticking to outdated investment strategies or avoiding the stock market due to a perceived safety in maintaining the status quo. Overconfidence Bias: People frequently overestimate their financial acumen or capabilities, leading to risky investments or the belief in their ability to predict market movements. Overconfidence can lead to unsound financial choices, such as incurring excessive debt or making speculative investments that don't align with long-term objectives. Present Bias: This bias prompts individuals to prioritize immediate gratification over future rewards. The satisfaction of spending money now outweighs the benefits of saving or investing later. Present bias can result in impulsive purchases, excessive spending, and inadequate saving for retirement or future objectives. Anchoring: When making decisions, individuals may rely too heavily on the initial piece of information they receive. For instance, if you first see a jacket priced at $500 and then a similar one for $200, you might view the $200 option as a bargain, regardless of its actual value. Anchoring can influence financial decisions regarding loans, salary expectations, and investment valuations. Herd Mentality: Financial decisions are often made based on the actions of others, especially in the absence of information or when feeling uncertain. This can lead to speculative bubbles, where individuals invest in assets simply because others are doing so, as seen in the dot-com bubble or the 2008 housing market crash. Herd mentality can also influence consumer spending, leading to the purchase of unnecessary items due to social influence. 3. The Consequences of Behavioral Biases on Financial Decisions Behavioral biases can result in various suboptimal financial actions with long-term negative effects. Here are some examples of how these biases impact financial decisions: Insufficient Retirement Savings: Due to present bias and procrastination, many people delay saving for
The Impact of Psychological Factors on Personal Finance: How Biases Influence Economic Choices
While personal finance might seem like a purely mathematical and logical domain, it is, in fact, significantly impacted by psychological factors and human behavior. Many economic decisions are not driven by rational analysis but are instead influenced by emotions, biases, and cognitive tendencies. Gaining insight into the psychological aspects of personal finance can assist individuals in making more informed and deliberate financial choices, which can result in improved financial health. This article delves into the behavioral biases that impact financial decisions, their manifestations in daily life, and tactics for overcoming them. 1. Emotional Influences on Financial Choices Emotions like fear, greed, and overconfidence greatly affect financial decision-making. These emotions frequently override logical thinking and can result in suboptimal financial choices. For instance, during a market downturn, fear might lead individuals to sell their investments at a loss in a panic, whereas during a bull market, greed could encourage individuals to take on excessive risk. Fear and Aversion to Loss: There is a tendency for individuals to dread losses more than they appreciate gains, a concept known as "loss aversion." This can deter people from taking necessary financial risks or lead them to cling to failing investments, hoping for a recovery, which often exacerbates their losses. Greed and Excessive Confidence: In a rising market, the desire for greater gains can obscure judgment. Individuals might overestimate their predictive abilities regarding market trends, leading to speculative investments or the accumulation of unsustainable debt levels. 2. Cognitive Biases in Economic Decision-Making Cognitive biases are mental shortcuts or thought patterns that can result in consistent errors in judgment. In personal finance, these biases often skew our perception of risk, reward, and timing, prompting irrational decisions. Anchoring Bias: This bias happens when individuals place too much weight on the initial information they receive, such as a stock's initial price or past investment returns. For example, an investor who bought a stock at a high price might irrationally cling to that price, waiting for it to return to that level before selling, even if market conditions have significantly changed. Confirmation Bias: This bias causes individuals to seek information that confirms their pre-existing beliefs while disregarding contradictory evidence. In finance, this could mean only engaging with financial news that aligns with one's market perspective or only following advisors who support their investment strategies. Availability Bias: People are prone to overestimating the likelihood of events based on how readily examples come to mind. For instance, after hearing about a friend's significant profit in the stock market, an individual might be more likely to take on excessive risks, overestimating their likelihood of success. Mental Accounting: This bias occurs when individuals categorize money into different "mental accounts" and treat it differently based on its source or purpose. For example, someone might be more willing to spend a tax refund frivolously but be more conservative with their regular income, even though the money is essentially the same. 3. The Endowment Effect: Overvaluing Our Possessions The endowment effect is the inclination for individuals to place a higher value on items they own simply because they possess them. This bias can result in poor financial decision-making, especially concerning investments or material possessions. Overvaluing Assets: Investors might retain underperforming assets because they overvalue them, believing they are worth more than the market indicates. This can lead to missed opportunities for reinvestment or diversification. Aversion to Selling: Similarly, homeowners might overvalue their property, refusing to sell at a fair market price due to emotional attachment, even though selling could benefit their financial future. 4. Present Bias: Favoring Immediate Rewards One of the most pervasive biases in personal finance is the present bias, which is the inclination to prioritize immediate rewards over future benefits. This bias leads individuals to make decisions that provide instant gratification at the expense of long-term financial health. Spending vs. Saving: The present bias often results in excessive spending and a disregard for saving